


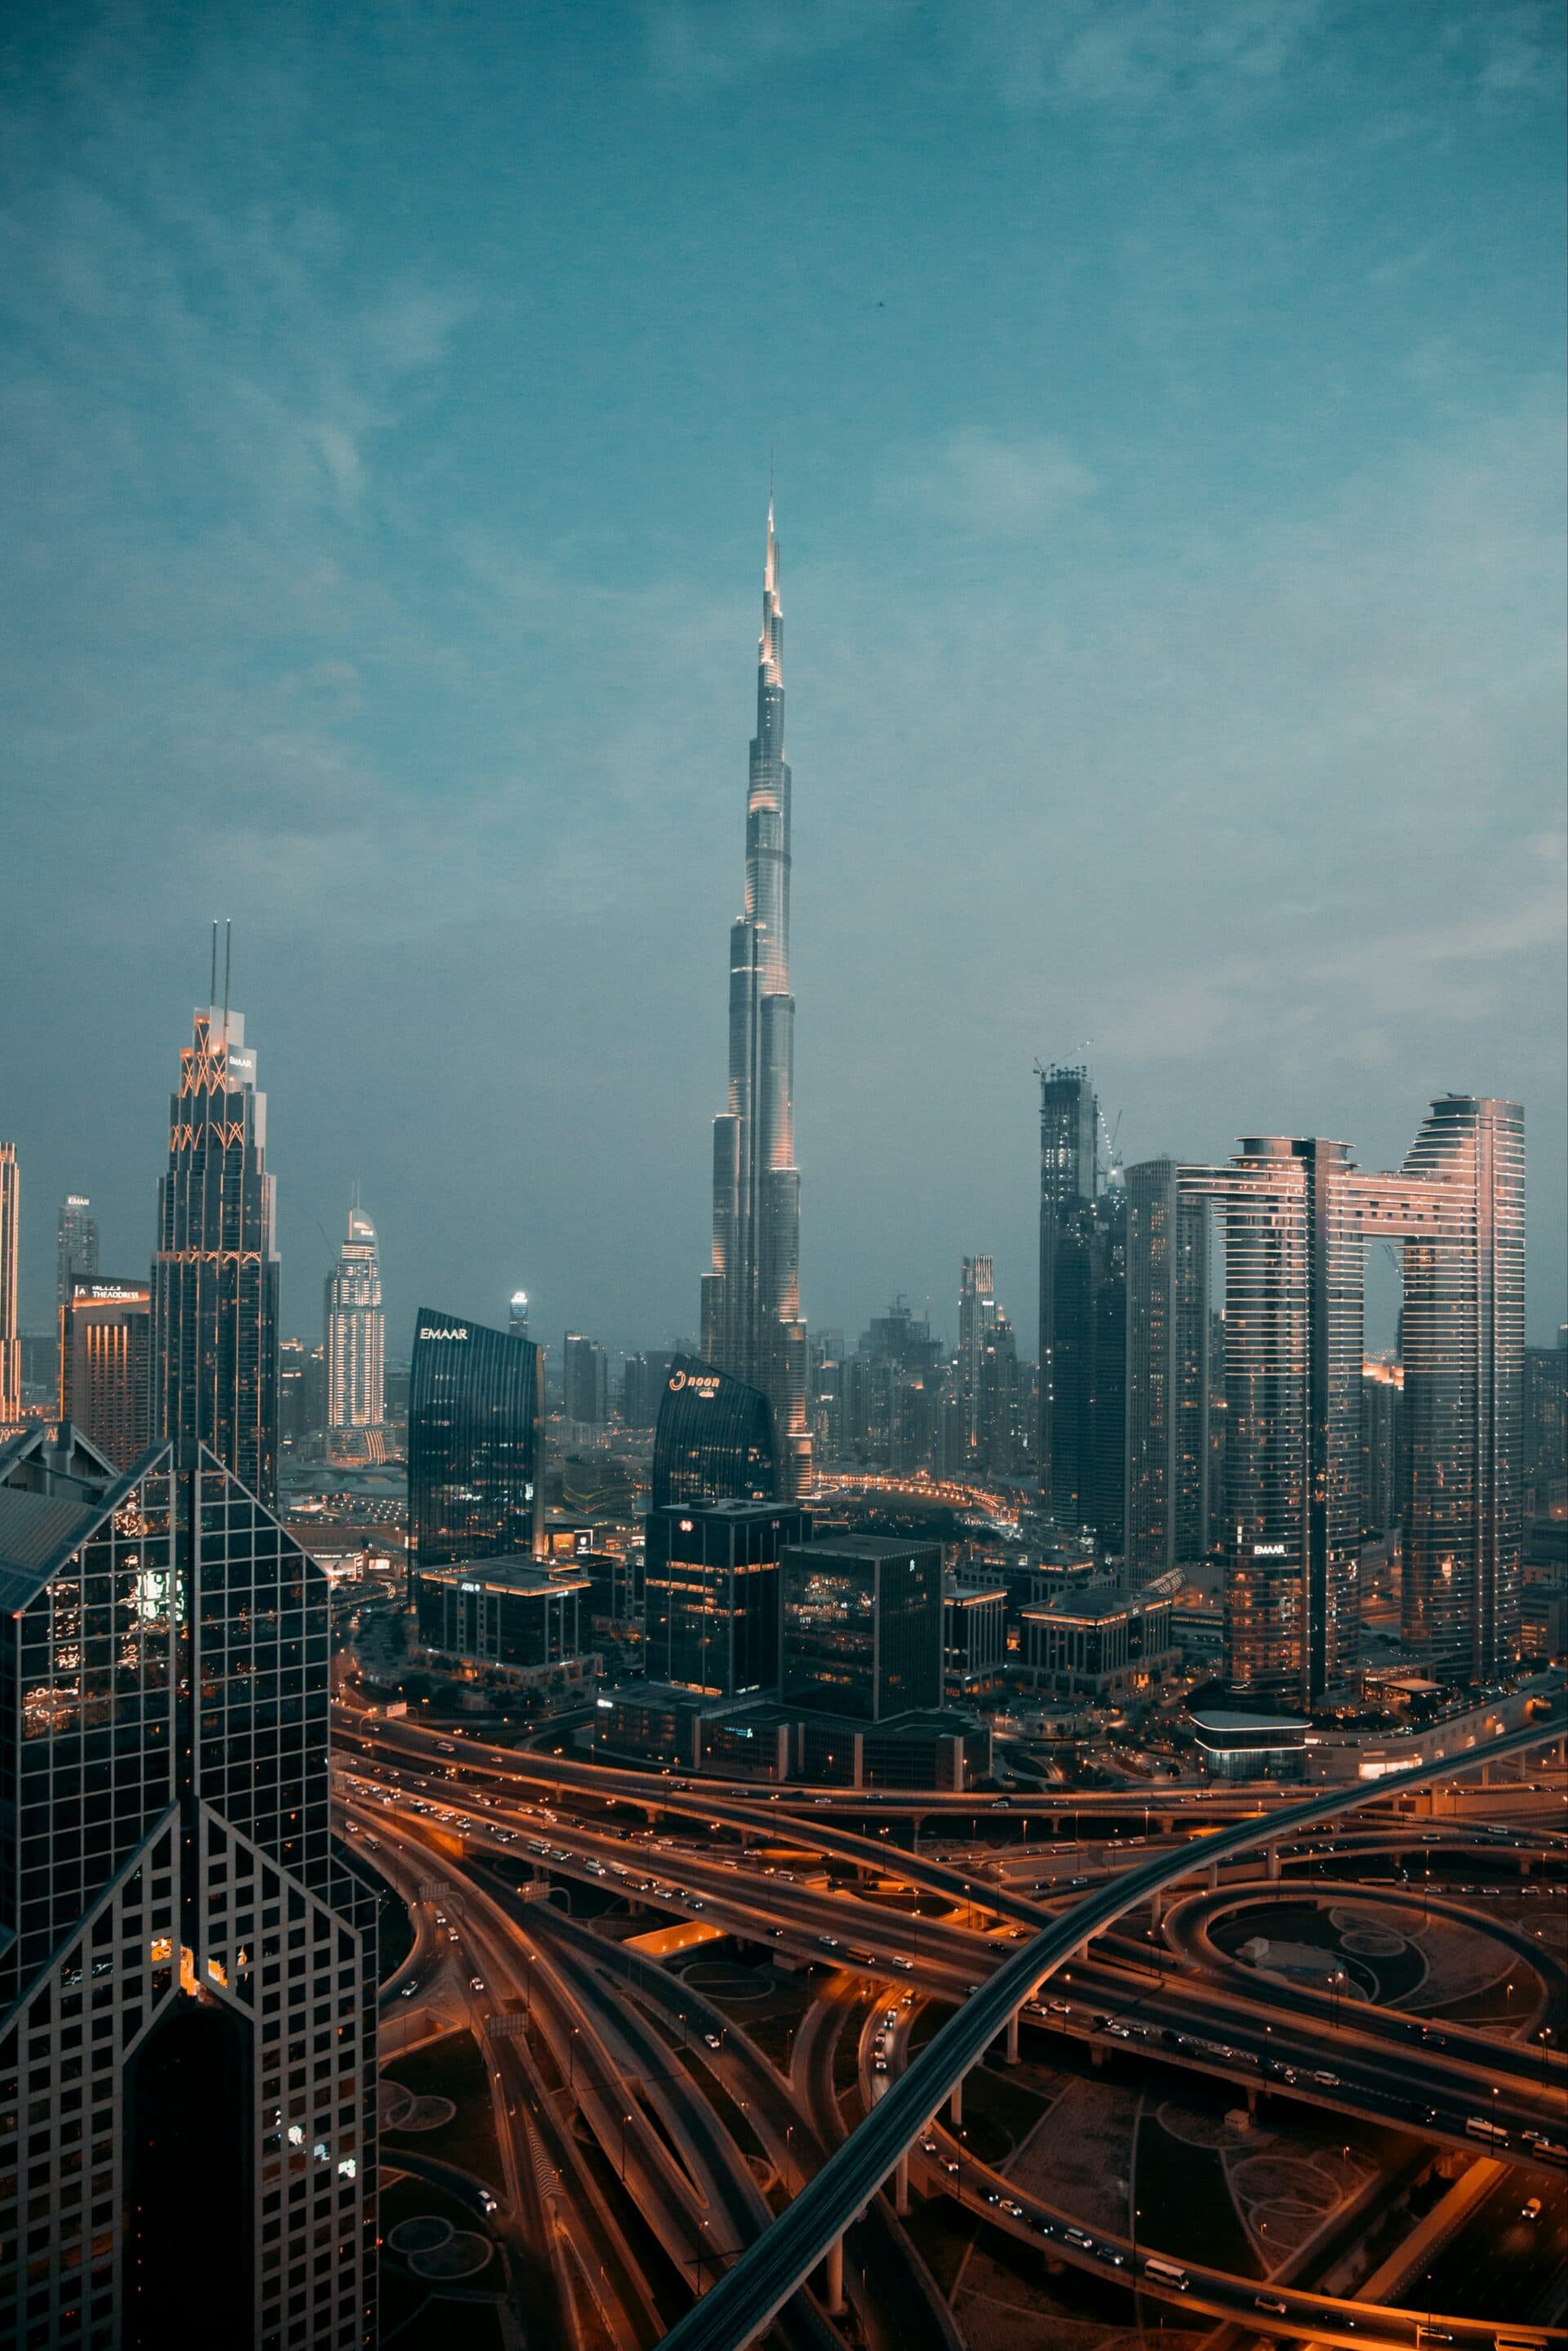
Setting up a company in Dubai means gaining access to one of the most attractive tax and business environments in the world. The emirate has established itself as a strategic hub between Europe, Asia and Africa, offering privileged access to fast-growing markets. World-class infrastructure, a digitalised administration and a competitive tax framework make it one of the most sought-after destinations for internationally minded businesses. But the right location still has to be chosen, the company properly structured and the whole arrangement aligned with French tax law.
This article offers a complete overview: UAE taxation, the strategic choice between free zone and mainland, the incorporation steps, operational friction points and interaction with French tax law.
I. The UAE tax framework: what has changed since 2023
A. Corporate Tax at 9%: the end of “zero tax” for companies?
Since 1 June 2023, the United Arab Emirates has had a corporate income tax (Corporate Tax) set at 9%[1], one of the lowest rates in the world, far below the 25% applied in France. Moreover, this rate applies only to the portion of profits exceeding AED 375,000 (around €95,000). Below this threshold, the rate is 0%.
In other words, a company whose annual profit does not exceed AED 375,000 pays no corporate income tax. For start-ups and small consultancy structures, this allowance is a considerable advantage, all the more so as there is still no personal income tax in the Emirates.
VAT, introduced in 2018 at a rate of 5%[2], applies to most commercial transactions, with a mandatory registration threshold of AED 375,000 in annual turnover.
B. Free zone vs mainland: two approaches, two tax regimes
The choice between free zone and mainland is the first strategic decision in any establishment in Dubai.
The free zones (46 to date) offer an environment dedicated to foreign investors: 100% foreign ownership, simplified procedures and, above all, a 0% Corporate Tax rate on “qualifying income”[3]. In practice, income from transactions with other free zone businesses or from foreign sources may be exempt, subject to meeting substance requirements.
On the other hand, free zone companies do not have direct access to the local UAE market. To sell to a customer located outside the free zone, they must go through a local distributor or bear additional logistics costs.
Setting up on the mainland, that is, registering with the Department of Economy and Tourism, allows direct access to the local market, participation in public tenders and a perception of solidity valued by banking partners. In return, Corporate Tax at 9% applies with no preferential regime.
Our practical recommendation
The choice of zone depends on your business and your target market. A consultant invoicing international clients will favour a moderately priced free zone such as IFZA. A commodities trader will turn to the DMCC. A company targeting the UAE market or public procurement has no alternative to the mainland.
II. The incorporation steps
A. From licence to first contract: a digitalised process
Setting up a company in Dubai follows a structured process, largely digitalised through the Basher platform[4]. The first step is to determine the nature of the business activity, as this determines the type of licence required (commercial, professional, industrial). The appropriate legal structure must then be chosen: limited liability company (LLC), joint stock company, branch, holding company or sole proprietorship.
Once these choices have been made, the investor reserves a trade name with the competent authority, then applies for initial approval from the UAE authorities. The constitutional documents are drawn up, and the company must have a physical registered office whose lease is registered through the EJARI system[5]. Once the complete application has been filed and the fees paid, the trade licence is issued and the business is registered with the Dubai Chamber of Commerce[6].
Certain regulated activities (healthcare, finance, telecommunications, energy) require additional sector-specific authorisations.
B. Economic substance and bank account: the real issues
Beyond the administrative process, two friction points deserve particular attention.
The first is the economic substance requirement. Since Cabinet Resolution No. 55 of 2023[7], companies established in the Emirates must demonstrate a genuine presence: physical office, qualified staff, management decisions taken locally. These obligations are intended to meet OECD international standards and prevent artificial arrangements. In practice, a mere postal address is no longer enough. The company must have an actual workspace and be able to demonstrate operational activity on the ground.
The second point, often underestimated, is opening a bank account. UAE institutions apply enhanced KYC and require detailed supporting documents: business plan, evidence of activity, source of funds and bank references from the country of origin.
Point to watch
A company that has been incorporated but has no local bank account is an empty shell: it cannot invoice, receive payments or demonstrate its economic substance. Opening the account must be anticipated from the very start of the incorporation process, and not treated as a formality at the end.
III. Interaction with French tax law
Setting up a company in Dubai does not necessarily mean cutting ties with France. In most cases, the entrepreneur retains a business, a customer base or an existing structure in France. The challenge is then to organise the coexistence of the two entities within a coherent tax framework.
The first question is that of permanent establishment. A UAE company managed from France, whose strategic decisions are taken in Paris or Marseille, risks being regarded by the tax authorities as having a permanent establishment in France, and therefore being taxed there. In practice, the effective management of the company must be exercised from Dubai: board meetings held locally, contracts signed locally, operational management carried out from the emirate.
Next comes the question of financial flows between the two structures. Intra-group services, management fees and dividend upstreaming must be carried out on arm’s length terms. In other words, each flow must correspond to a genuine service, documented and invoiced at a market price. Failing this, the tax authorities may challenge the terms of the transaction under the transfer pricing rules.
In this context, the tax treaty between France and the UAE of 19 July 1989 allocates taxing rights between the two States and, in this respect, provides a protective framework for entrepreneurs who structure their establishment correctly. In particular, it makes it possible to avoid double taxation of profits and income flowing between the two jurisdictions.
Nevertheless, the French tax authorities have extensive audit powers and benefit from the automatic exchange of information mechanisms (CRS) introduced under the aegis of the OECD. A UAE company held by a French tax resident must be declared (form No. 2047, declaration of foreign accounts No. 3916). In practice, the arrangement must be coherent as a whole: the Dubai company must meet a genuine economic need, have substance on the ground and form part of a documented internationalisation strategy. Failing this, the risk of recharacterisation or tax reassessment is real.
***
Dubai remains one of the most attractive destinations for French entrepreneurs wishing to expand internationally. Even after the introduction of Corporate Tax in 2023, the tax framework remains competitive, and the business ecosystem is designed to facilitate company formation. But appeal is no substitute for rigour: the choice of zone, economic substance, opening a bank account and interaction with French tax law are all parameters that determine the success of the project.
Bruzzo Dubucq assists French entrepreneurs and investors in structuring their establishment in Dubai, from the preliminary tax analysis to the actual incorporation of the company.
[1] Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses, in force since 1 June 2023.
[2] Federal Decree-Law No. 8 of 2017 on Value Added Tax (VAT).
[3] Federal Decree-Law No. 47 of 2022, Art. 18 (Qualifying Free Zone Person).
[4] Basher platform (Business Activities and Services Hub for Entrepreneurs and Residents), operated by Dubai’s Department of Economy and Tourism.
[5] EJARI: the mandatory lease registration system in Dubai, managed by the Real Estate Regulatory Agency (RERA).
[6] Dubai Chamber of Commerce and Industry.
[7] Cabinet Resolution No. 55 of 2023 concerning the Economic Substance Requirements.











